Insurance Basics
Insurance Deductibles Explained: What You Need to Know

Introduction
Understanding insurance terminology, such as “deductibles,” is crucial to making informed choices about your coverage. The word “deductible” can be confusing, especially for those who are managing policies or filing claims. The deductible is a key part of how Insurance Deductible works. It determines not only the amount you pay upfront but also your overall coverage costs.
This article will answer all your questions about deductibles and how they impact financial planning. This article will help you understand the basics, such as what deductibles are and how they affect premiums.
Understanding Insurance Deductibles
A deductible is essentially the amount you agree to pay yourself out-of-pocket for a claim before your insurance covers the rest. Imagine it as a share of your financial responsibility in case of a claim. The deductibles create a balance. They protect the insurer from having to cover small or frivolous claims while keeping premiums affordable.
If your auto insurance policy has $500 in deductibles and the cost of an accident repair is $2,000, then you would pay $500 and your insurer would cover the rest. Deductibles are applicable to many types of insurance policies, including auto, health, renters, and homeowners. They play an important role in determining your relationship with coverage.
Different Types of Insurance Deductibles
The type of insurance you have will determine the deductibles. In the case of auto insurance and homeowners’ insurance, deductibles usually consist of dollar amounts. These are fixed sums you must pay in order to receive benefits. In contrast, health insurance often has annual deductibles. This means that you have to pay this amount in full over the course of a year.
Some policies have deductibles that are based on a percentage, particularly in areas susceptible to natural disasters. A homeowner, for example, might have a policy that has a deductible of 2% of their insured home value in the event of damage from hurricanes or an earthquake. Different formats of deductibles may influence the behavior of policyholders, since higher deductibles often lead to lower insurance premiums but also require more out-of-pocket expenses in case of a claim.
How Do Deductibles Impact Premiums?
When it comes to deductibles, there’s a simple formula: the higher your deductible is, the lower the monthly premium. This is because insurance companies can reduce their costs by reducing the deductible.
A lower premium might seem attractive, but a plan with a higher deductible is not always the best choice. Consider whether you can comfortably afford to pay more out of pocket if an unexpected event occurs. It is important to balance deductibles and premiums in order to ensure that your policy matches your financial situation and your risk tolerance.
Selecting the Right Deductible
When choosing the right deductible, you should consider your financial situation and your willingness to accept risk. You may choose a lower-cost plan if you are financially stable and can afford a higher deductible. If you find it difficult to pay a large out-of-pocket amount, you might prefer a plan with a lower deductible, even if the recurring premiums are higher.
Your lifestyle matters, too. If you have a low claim rate and a good driving record, for example, you could save money by increasing your deductible. Review your policy and evaluate past experiences in order to find the right balance between protection and affordability.
Deductibles and the Claims Process
It is important to know how the claims process works when there is a deductible. When you make a claim, the deductible is deducted from your claim payment. If the cost of the damages or losses is less than the deductible amount, then your insurance will not contribute to the costs. You’ll have to pay the full cost.
If a homeowner has a $1,000 deductible and their property is damaged for $750, the insurer will not pay out because the cost is less than the $1,000 deductible. If the total damage is $5,000, then the $1,000 deductible would be subtracted from the payout, and the insurance company would pay $4,000. Understanding your deductible can eliminate unpleasant surprises and help you make an informed decision about whether or not to file a claim.
How to Manage Deductibles
Understanding the role of deductibles in your insurance policy is essential to managing them effectively. You should keep track of the deductible and have enough money in your savings account to cover this amount in an emergency. Building a separate emergency fund for deductibles can give you peace of mind and protect your financial health.
A useful strategy is to review your policies periodically and make sure that they are still in line with your current financial or life situation. You can optimize your premiums by adjusting your deductible to your current needs. If your current policy feels unsustainable, you can compare rates and look for a better deal.
Prepare for Potential Claims
It’s important to prepare for any potential claims. Document your belongings regularly, especially for renters or homeowners insurance. A detailed inventory will streamline the claim process and help you receive proper compensation.
Become familiar with the rules and procedures of your insurer for filing claims. Understanding your policy’s fine print will help you avoid having a claim rejected. Strong communication with your insurer will ensure that you are prepared to handle any incident.
Empower Yourself with Knowledge
Knowing about deductibles when it comes to insurance is essential for customizing coverage that suits your needs. These cost-sharing mechanisms are crucial in determining the affordability and usability of your policy. Understanding deductibles will help you make more informed decisions, better manage your risks, and be prepared for the uncertainties of life.
Review your insurance policies to see if your current deductibles are working in your favor or if you need to make changes. You can now approach your insurance policy with more confidence and peace of mind.
FAQs
1. Why are insurance policies subject to deductibles?
Deductibles help you keep your premiums low while reducing unnecessary claims.
2. Do higher deductibles save money on insurance premiums?
It depends on whether you are financially prepared to pay for larger out-of-pocket expenses in the case of a claim.
3. After purchasing an insurance policy, can I change my deductible?
Many insurers will allow you to adjust the deductible depending on your personal financial situation, but it could affect your premium.
4. How do health insurance deductibles differ?
The health deductibles can be cumulative. This means that you have to reach the total amount before any benefits, such as co-pays or coverage, kick in.

Living abroad can open doors to new careers, experiences and opportunities. But for many Kenyans in the diaspora, moving away does not mean leaving Kenya behind. Home is still home. Your parents may still be here. You may want to invest in Kenya, buy property, support family, build wealth or eventually return home. And from time to time, you may simply need someone reliable to help you get something done in Kenya.
The problem? You could be thousands of kilometers away. That distance can turn what should be a simple decision into a difficult one.
Who do you trust? How do you verify an opportunity? And who can you rely on when you cannot be there yourself?
These are some of the realities that My Diaspora Nexus was created to address.
What Is My Diaspora Nexus?
My Diaspora Nexus is a membership platform designed for professional Kenyans living abroad.
It brings together services, opportunities, connections and support designed around a simple reality: even when you live outside Kenya, a significant part of your life may still be connected to home.
Instead of navigating every need independently, MDN is building an ecosystem where members can access trusted solutions across family protection, wealth creation, real estate, professional and personal connections, and everyday services in Kenya.
The platform is built around three pillars: Trust. Professionalism. Compassion.
Trust When Dealing With Kenya From Abroad
When you live abroad, you cannot always inspect a project, meet a service provider or follow up on an opportunity in person.
That makes trust essential. MDN focuses on vetting, due diligence, reliable partners and greater transparency to help members approach important decisions with more confidence.
Professionalism in Service and Support
Kenyans living abroad often operate in environments where clear communication, accountability and service standards are expected. MDN aims to bring that same mindset into how members are served, how partners are selected and how services are delivered.
Compassion and the Power of Community
The diaspora story is not only about success. Behind every member is a family, a responsibility, an ambition and sometimes an unexpected challenge. MDN therefore also recognizes the importance of community and supporting members through different stages of the diaspora journey.
Five My Diaspora Nexus Products for Kenyans Abroad
1. My Diaspora Care: Protecting What Matters
Family remains one of the strongest connections many Kenyans abroad have to home. But bereavement and serious emergencies can arrive without warning. My Diaspora Care is centered on Last Expense Insurance Protection for enrolled members and eligible family beneficiaries. Members enrolled in the cover can also access Community Benevolence Support for compelling and verified emergency situations. The goal is to help members and their families be better prepared when difficult moments come.
2. My Diaspora Investment Club: Building Wealth Together
Earning money abroad is one thing. Building sustainable, long-term wealth is another. My Diaspora Investment Club brings together diaspora professionals who want to develop a more disciplined approach to investing. Members contribute towards a growing investment portfolio, track their progress and participate in a community focused on long-term financial growth.
It is a shift from simply contributing money to intentionally building wealth.
3. My Diaspora Real Estate: Investing in Kenya With Greater Confidence
For many Kenyans in the diaspora, owning property back home is an important goal. But investing in Kenyan real estate from abroad can raise difficult questions. Is the developer credible? Has the project been properly verified? Will construction be completed? Is the documentation in order?
My Diaspora Real Estate is designed to help members navigate those questions through due diligence, vetted developers and projects, member feedback and ongoing partner monitoring. Instead of relying entirely on advertisements and promises, members can access more information to support their property investment decisions.
4. My Diaspora Connect: Building Meaningful Connections
Not every diaspora challenge is about money or property. Relationships matter too. Living abroad can make it harder to build professional networks, discover business opportunities or create meaningful personal relationships. My Diaspora Connect provides a trusted environment where members can seek professional connections, collaborations, referrals, mentorship, friendships and other meaningful personal connections. Because sometimes one good connection can open an entirely new opportunity.
5. My Diaspora Essentials: Getting Things Done Back Home
Sometimes you do not need an investment. You simply need something done in Kenya. Maybe you need a contractor. Perhaps you are sourcing a vehicle, looking for a professional service or managing something related to property or family. From abroad, even a simple task can become complicated when you do not know who to trust. My Diaspora Essentials gives members access to a vetted network of service providers, businesses and professionals, helping them find reliable solutions without having to start their search from scratch every time.
Staying Connected to Kenya Should Be Easier
Living outside Kenya should not mean figuring out everything back home alone. Whether your priority is protecting your family, investing in Kenya, buying property, building wealth, creating meaningful connections or finding reliable services, My Diaspora Nexus is building a platform around those realities.
My Diaspora Nexus: Supporting Kenyans Abroad
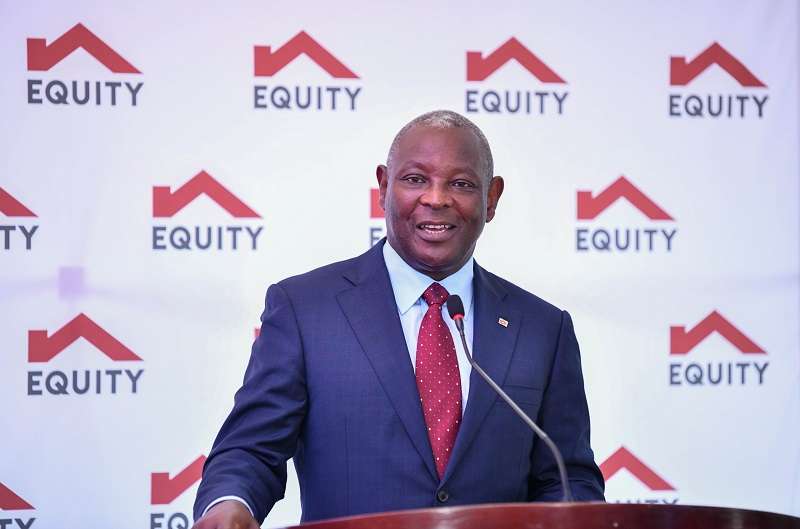
For years, African banking expansion was largely measured by branch networks, national dominance, and balance-sheet growth. Equity Group Holdings is now pushing a far more ambitious idea: scale without borders.
The Nairobi-based lender says it wants to operate in 15 countries and serve 100 million customers by 2030, a target that would place it among the most expansive financial institutions ever built on the continent. The announcement came as the group reported its strongest first-quarter performance on record, crossing the KSh 2 trillion asset threshold for the first time while posting sharp growth in profits, deposits, and regional operations.
What stands out is not simply the pace of growth. It is where that growth is increasingly coming from.
For the first time, Equity’s subsidiaries outside Kenya contributed more than half of the group’s assets and profit before tax — a symbolic milestone for a bank that built its reputation serving low-income and previously unbanked customers in Kenya before evolving into a regional financial powerhouse.
Group Managing Director and CEO Dr. James Mwangi said the lender, which currently serves 22.7 million customers across six countries, is targeting 15 countries and 100 million customers by 2030 through organic growth and acquisitions.
That strategy reflects a broader shift underway in African finance. The continent’s most aggressive banks are no longer thinking like domestic institutions with regional outposts. They are increasingly behaving like pan-African platforms competing for influence across trade corridors, mobile payments, SME lending, insurance, and digital infrastructure.
In many ways, Equity’s trajectory mirrors the evolution of African telecom giants over the past two decades — companies that expanded beyond saturated home markets into faster-growing economies with younger populations and lower banking penetration.
The Regional Bet Is Paying Off
The latest results suggest Equity’s regional diversification strategy is beginning to mature.
Operations outside Kenya now account for a majority share of the group’s business, reducing its dependence on a single economy at a time when East African markets are experiencing uneven inflation, currency pressures, and shifting interest-rate environments.
The Democratic Republic of Congo has emerged as a particularly important growth engine. Equity BCDC, the group’s Congolese subsidiary, remains its largest operation outside Kenya and continues to benefit from a vast underbanked population, strong demand for trade finance, and growing formalization within parts of the economy.
Tanzania also delivered standout growth, recording rapid expansion across loans, deposits, and profitability. That performance matters because Tanzania has historically been a difficult market for foreign banks seeking meaningful scale. Strong execution there signals Equity may be improving its ability to localize operations rather than simply replicating its Kenyan model abroad.
Uganda, meanwhile, was the lone weak spot in the quarter, highlighting a reality often overlooked in investor conversations about African banking: regional expansion can amplify risk just as easily as it amplifies opportunity.
Operating across multiple African jurisdictions means navigating different regulatory systems, currencies, tax structures, and political environments simultaneously. A slowdown in one market can quickly offset gains elsewhere.
Still, the broader direction is unmistakable. Equity is evolving from a Kenyan bank with regional subsidiaries into a regional institution with Kenyan roots.
Digital Banking Is Quietly Reshaping the Economics of Growth
One of the most consequential details in the earnings report received comparatively little public attention: nearly 90% of transactions are now happening through digital channels.
That statistic helps explain how Equity can realistically pursue 100 million customers without building thousands of expensive physical branches.
Traditional banking expansion relied heavily on brick-and-mortar infrastructure, which made continental scale extraordinarily costly. Digital banking changes the economics entirely. Customer acquisition becomes faster, operating costs decline, and services can expand into underserved markets without waiting for physical infrastructure investment.
This is especially important in Africa, where mobile penetration has dramatically outpaced traditional banking access.
According to the World Bank financial inclusion overview, digital financial services have become one of the continent’s most important tools for bringing unbanked populations into the formal economy. Kenya, in particular, has often been cited globally as a leading example of mobile-money-driven financial inclusion.
Equity’s digital lending growth also reveals another strategic advantage: data.
Banks with large digital ecosystems gain access to transaction behavior, repayment patterns, and customer activity at a scale that smaller institutions struggle to match. That data increasingly shapes credit scoring, insurance underwriting, and cross-selling opportunities.
In practical terms, the future African banking battle may not be fought primarily over branches or even deposits. It may be fought over ecosystems — who controls the customer’s daily financial activity across payments, credit, savings, insurance, and business services.
Why Investors Are Watching Asset Quality Closely
Despite the strong headline numbers, investors are unlikely to ignore one key issue: non-performing loans.
Equity’s bad loan ratio improved significantly year-on-year, but it still remains above management’s long-term target range. That matters because rapid expansion often creates pressure to grow lending aggressively, especially in frontier markets where credit information systems can be weaker.
African banks have historically struggled with balancing growth ambitions against loan-book quality. Periods of rapid expansion are often followed by painful cleanups when economic conditions tighten.
Equity appears determined to avoid that pattern. The decline in loan loss provisions and stronger IFRS coverage indicate management is prioritizing balance-sheet resilience alongside growth.
That balancing act will become increasingly important as the bank pushes deeper into higher-risk but faster-growing markets.
The wider banking sector is also operating in a more complex environment globally. Rising geopolitical uncertainty, currency volatility, and pressure on emerging-market debt are forcing lenders to rethink risk exposure across regions. Recent analysis from the International Monetary Fund financial sector analysis has warned that tighter financial conditions continue to test banking systems in developing economies.
More Than a Bank
Equity’s evolution into insurance, health coverage, and digital financial services reflects another major shift happening across African finance: the rise of the financial super-platform.
Banks increasingly want customers to remain inside a single ecosystem for everything from loans and payments to insurance and investment products. The strategy deepens customer loyalty while creating multiple revenue streams beyond traditional interest income.
That matters because banking margins are changing globally. Digital competition is compressing fees, fintech startups are targeting profitable niches, and younger consumers increasingly expect low-cost financial services delivered instantly through smartphones.
Equity’s answer appears to be scale, diversification, and ecosystem depth.
The group’s first-quarter results suggest that strategy is working — at least for now.
What happens over the next few years may determine whether Equity becomes merely East Africa’s dominant bank or one of the defining financial institutions of modern Africa.
For readers tracking the broader evolution of African banking and regional finance, the African Development Bank regularly publishes research on financial integration, digital banking, and economic growth trends across the continent.
Insurance Basics
High Court to Rule on Gachagua Impeachment Case as Kenya Awaits Major Constitutional Test
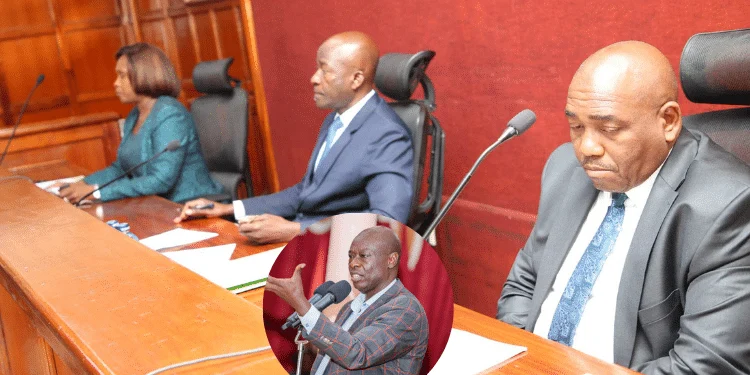
Kenya’s political and legal establishment is now focused on 8 June, when the High Court is expected to deliver its judgment in former Deputy President Rigathi Gachagua’s challenge to his impeachment — a decision likely to shape how future removals from high office are handled under the Constitution.
The ruling, set to be delivered at the Milimani Law Courts in Nairobi, follows five days of hearings before a three-judge bench comprising Justices Eric Ogolla, Freda Mugambi, and Anthony Mrima.
At the centre of the case is a question that extends far beyond one political figure: how far Parliament and the Senate can go in removing a deputy president before constitutional protections around due process, public participation, and fair hearing are tested.
More on Kenya’s judicial system and constitutional framework can be found through the Kenya Judiciary.
Gachagua’s case rests on process, not just politics
Rigathi Gachagua argues that his October 2024 impeachment violated constitutional safeguards and was conducted in a manner that denied him a meaningful opportunity to defend himself.
His legal team contends that the proceedings moved too quickly, limiting public participation and undermining procedural fairness during one of the most consequential constitutional processes available to Parliament.
The former deputy president is also seeking compensation equivalent to the salary and benefits he would have earned had he completed his term following the 2022 election.
His lawyers further relied on medical evidence presented by cardiologist Daniel Gikonyo, who told the court that Gachagua’s illness affected his ability to participate fully during Senate proceedings.
The case therefore combines political conflict with constitutional interpretation, creating what legal observers view as one of the most important institutional tests since the promulgation of Kenya’s 2010 Constitution.
Parliament and Senate defend the impeachment process
Lawyers representing Parliament and the Senate have rejected claims that the process was unconstitutional, arguing that all legal requirements were followed and that Gachagua had legal representation throughout the proceedings.
According to the respondents, the former deputy president was accorded a fair hearing and given sufficient opportunity to respond to the allegations against him.
Kithure Kindiki’s legal team also challenged the argument surrounding illness, maintaining that medical concerns did not invalidate Senate proceedings or justify postponement of the process.
Their position reflects a broader institutional argument: that constitutional impeachment mechanisms must remain functional and enforceable without being indefinitely delayed through procedural objections.
Further reading on constitutional governance and separation of powers in Kenya is available through the Katiba Institute.
Why the ruling matters beyond Gachagua
While the case is politically charged, the judgment’s long-term significance lies in the precedent it may establish for future impeachments and executive accountability.
If the court rules in Gachagua’s favour, it could raise the threshold for removing senior state officials by requiring stricter procedural standards, expanded public participation, and broader protections around fair hearing rights.
A decision upholding the impeachment, however, would reinforce Parliament’s authority in exercising oversight over top executive offices and potentially solidify impeachment as a politically viable accountability mechanism.
Either outcome is likely to influence how future political disputes are handled within constitutional institutions rather than through purely political negotiation.
A defining moment for Kenya’s constitutional order
The impeachment of a deputy president is still relatively untested territory under Kenya’s current constitutional framework, making the upcoming ruling particularly significant for legal scholars, political actors, and governance institutions.
The court’s interpretation may shape not only executive accountability, but also the balance of power between Parliament, the Senate, the judiciary, and the presidency itself.
That broader institutional impact explains why the case continues to attract national attention even beyond partisan politics.
More on constitutional interpretation and governance developments in Kenya can be followed through the Kenya Law Reports.
Political consequences likely regardless of outcome
Even before the ruling is delivered, the case has already intensified debate over executive power, parliamentary oversight, and the use of impeachment in Kenya’s evolving political system.
For supporters of Gachagua, the case represents a test of whether constitutional safeguards can withstand political pressure. For his opponents, it is a test of whether senior state officers can be held accountable through established legal mechanisms.
The June 8 judgment is therefore unlikely to end the political conversation. It may instead define the next phase of it.
Tags: Rigathi Gachagua, Kenya High Court, impeachment case, Kithure Kindiki, Kenya politics, constitutional law Kenya, Milimani Law Courts

Kenyan woman Stella Wamaitha Njoroge says one act of kindness in Dubai changed her life

DHS proposes $70,000 fee for international students seeking U.S. work experience

Undergraduate Scholarships for Kenyan Students: Bob Mwiti’s Powerful Guide to a Brighter Future

VIDEO: iPhone 17 Air Leak Reveals Ultra-Thin Design: A Bold Leap Beyond the iPhone 16 Pro

How U.S. Remittance 5% Tax Bill Could Impact Kenyan Diaspora: What You Need to Know

Motorola Launches $1,300 Razr Ultra Foldable Smartphone with AI Features, Swarovski-Enhanced Earbuds

 Tech1 year ago
VIDEO: iPhone 17 Air Leak Reveals Ultra-Thin Design: A Bold Leap Beyond the iPhone 16 Pro
- News1 year ago
How U.S. Remittance 5% Tax Bill Could Impact Kenyan Diaspora: What You Need to Know
- Tech1 year ago
Motorola Launches $1,300 Razr Ultra Foldable Smartphone with AI Features, Swarovski-Enhanced Earbuds
- Insurance Basics1 year ago
Popular Apps May Be Secretly Tracking Your Driving – And Raising Your Insurance Rates
- Tech1 year ago
Motorola Razr Ultra (2025) Launches With Free 1TB Storage Upgrade
- News1 year ago
What would you do if your Gold Digger girlfriend behaved like this?
- News1 year ago
Box Office: ‘Sinners’ Holds No. 1 Spot With $13M Friday; ‘The Accountant 2’ Debuts With $9.4M
- Insurance Basics1 year ago
Florida House Passes ‘Pam Rock Act’ Requiring Dog Registry and $100K Liability Insurance